TECHNOLOGY · ANALYTICS · INVESTMENT RESEARCH
Phat Ngo.
I build tools that make data easier to understand and decisions easier to explain.
Senior Technology Consultant at EY. M.S. Analytics student at Georgia Tech. Exploring systematic investing through personal research.
- Professional experience
- EYSenior Technology Consultant
- Analytical foundation
- Georgia TechM.S. Analytics · Expected May 2027
- Working tools
- Python · SQL · RData, research, and decision support
Selected work.
Two research tools and the experience behind them.
- PERSONAL RESEARCHTry a strategy
Strategy testing
Test a trading rule against past prices. Explore simulated outcomes or track it against new data.
- PERSONAL RESEARCHView markets
Market monitoring
Understand rates, the yen, and US stocks. See the source behind each number and explore what could change.
- PROFESSIONAL EXPERIENCEView resume
Technology consulting
My work at EY connects enterprise data, reporting, and automation to business decisions.
Research tools are demonstrations. Historical and simulated results are not a live investment record.
Project notes and methods
Additional project background
01SYSTEMATIC INVESTINGFutures & portfolio research
Futures & portfolio research
Personal work on automated equity-index futures strategies and portfolio allocation, with evaluation through Sharpe, Sortino, and drawdown analysis.
RESEARCH FOCUS
Project background Separating signal from noise. Understanding how execution costs, position sizing, and changing market conditions affect a strategy.
02ALTERNATIVE DATAFinding signal in financial language
Finding signal in financial language
Georgia Tech research applying topic modeling and regression to corporate earnings-announcement text and its relationship to firm outcomes.
RESEARCH FOCUS
Research background Testing whether the language companies use carries useful information beyond conventional numerical features.
03DECISION INTELLIGENCEFrom enterprise data to decisions
From enterprise data to decisions
Enterprise analytics, executive reporting, and data governance work developed through technology consulting at EY.
RESEARCH FOCUS
Experience background Making complex data useful to decision-makers, with clear measures, traceable inputs, and accountable processes.
DECENNIUM / PERSONAL RESEARCH
Strategy testing.
Start with past prices. Use simulations and paper tracking to investigate further.
BACKTEST
A backtest checks how a rule would have performed in the past, after assumed costs.
BACKTEST / USING PAST PRICES
Historical experimentWould this strategy have helped?
Choose a rule and market, then run the test. Compare the result with buying and holding the same market.
Your results will appear here.
Select Run backtest above to compare your rule with buying and holding.
RESULTS / FOUR HISTORICAL TEST PERIODS
See how the test was calculated
Rules, assumptions and limitations
Protect the sequence.
The first 60% of bars establish the initial training set. Four historical test windows cover the remaining return intervals. Parameters are reselected on expanding training data using a common 150-bar warm-up. Signals use prior closes and execute at the next open.
Trend candidates: 10/30, 20/60, 50/150-day averages. Breakout candidates: 20/10, 40/20, 60/30-day entry/exit channels. Mean-reversion candidates: a 20-session average with a 1.5 or 2 standard-deviation entry threshold, or a 60-session average with a 2 standard-deviation threshold. The signal close is excluded from the reference window. Exit on recovery to the mean or after 20 held sessions. Selection ranks training Sharpe with a zero risk-free rate.
Keep the claim narrow.
Growth compounds the four test windows; each starts flat and ends with liquidation. Both strategy and buy-and-hold pay boundary costs. Unadjusted prices omit distributions, cash interest, financing, taxes, and market impact.
Window spreads are strategy minus benchmark returns in percentage points. A later decline is descriptive evidence of instability, not a measured pattern half-life, proof of causation, or a significance test.
Know when to step back.
Proposed review triggers: advantage disappears after plausible costs, results depend on one window, the economic mechanism changes, or input quality fails. Suspend the hypothesis for review; document the reason before revising it.
Repeated runs are exploratory. Independent replication, multiple-testing controls, and a separate paper observation period are required before considering allocation.
Explore the historical baseline study
Follow an idea from its research question to a human review. This demonstration tests historical prices; trading is not connected.
Lead
Set the questionIdleResearch
Build the ideaIdleOptimization
Tune on earlier dataIdleBacktesting
Test unseen dataIdleLead review
Challenge the resultIdleDeploy
Human approvalIdle
03 / OBSERVE THE EVIDENCE
Holdout growth of $100
Loading verified market history…
Move across the chart to inspect observations.
DAILY CLOSE · USDInspect chart data
| Date | Price (USD) | Benchmark | Position |
|---|
REPRODUCE & REVIEW
Run the study, export its input bars and research record, and inspect the exact calculation code. The selected dates and results appear below after data loads.
Read the study methodDownload strategy engineDownload benchmark calculations04 / INVESTMENT COMMITTEE READOUT
What survived the test?
DECISION SUMMARY
Evaluating the evidence
EVIDENCE STATUS
Next research step: test independent periods, incorporate distributions, and examine sensitivity to execution assumptions.
Challenge before allocating.
| Fast / slow | Train Sharpe | Drawdown |
|---|
Selection sees training data only. Re-running after inspecting results makes this holdout part of your research history; it is no longer a fresh independent test.
Agent activity & methodology
A close-based signal uses information through the preceding session and executes at the next open. Returns run open-to-open. Both portfolios begin flat and liquidate at the final open. Costs apply on entry and exit. Sharpe uses 252 observations per year and a zero risk-free rate. All three candidates share the same training window after 150 warm-up observations. There is no leverage, shorting, dividends, cash interest, or modeled market impact. This is an educational research demonstration, not Phat’s investment track record.
Want to see how much outcomes can vary?
Try a simulationMONTE CARLO SIMULATION
Next: track new observationsWhat could happen to $100?
Choose a market to see 500 simulated journeys for an imaginary $100. Each journey rearranges returns from real price history. The range helps you explore uncertainty; it does not predict the future.
This simulation uses market returns. For a strategy’s simulated returns, run a strategy test and select Monte Carlo in its results.
Ready to follow a fixed rule against new prices?
Open paper trackingHOW THE SYSTEM WORKS
Rules-based demonstrationResearch an idea. Then watch it unfold.
The system checks public sources and three fixed strategies. You choose which idea to track. It then records new prices so you can see what happens after that choice.
You make the research decision.
The software gathers and checks evidence. Paper tracking starts only when you choose a rule. It uses an imaginary $100; no money is invested.
Learn from new observations. Keep the original rule fixed so you can judge it fairly. A different rule is a new experiment.
What runs automatically, and what does not
Built on available public sources
The loop checks the price histories, official releases, macroeconomic observations and BIS research feed already used by this site. No API key or additional account is needed. Observation dates and saved-data labels remain visible.
Each cycle compares completed QQQ, SPY and TLT observations with three predefined rules: trend, mean reversion and breakout. It prepares a research question, shows the measured condition, and gives a counterargument. A condition is not a validated edge.
Automatic checks, inspectable reasoning
Headlines are grouped by explicit topic keywords. This is not sentiment analysis, a reading of the full release, or a measure of policy surprise. Research titles link to the original papers; their findings are not inferred from a headline.
Checks run every 15 minutes while the Site is open and online. The Hostinger Node package also checks while its server is running. The workflow is rules-based software, without a connected language model or brokerage. Reddit and X are not included in this version.
CHOOSE AN IDEA TO TRACK
Start a paper test.
Read the sources and simulation results
No research cycle has completed yet.
FORWARD TESTING / NEW DATA ONLY
What happened after the test started?
Compare the rule’s imaginary $100 with buying and holding the same market. A new test waits for future data, so results will not appear immediately.
Loading registered experiments…
How new observations are recorded
The server records the registration time before accepting subsequent completed sessions. Each check accepts only the latest eligible close; it never fills in past sessions. A decision recorded after one close can be applied only at a later observed close. Missed checks therefore delay paper actions.
Daily prices must come from a source response, be no more than four days old, and fall after the registration date. The first eligible close establishes the $100 baseline. Strategy costs are deducted on position changes; buy-and-hold pays its entry cost. Open holdings have no assumed exit cost. Dividends, cash interest, financing, taxes and market impact are excluded.
This is delayed, close-based paper accounting, not a live order or an executable fill. A short forward record cannot establish an enduring edge. Mean reversion exits after recovery or 20 observed held sessions; this count pauses when no new data is accepted.
The process is inspectable. A conversation is the place to challenge its assumptions.
Discuss this projectWhat I want to research next
These six areas guide future research. Select one to see the question, the evidence it needs, and what could disprove it. They do not feed the current price strategies.
SIX LENSES / ONE RESEARCH QUESTIONWhat changes before the market changes its mind?
MARKET OBSERVATION / DATED EVIDENCE
Market monitoring.
Rates, currencies, and stocks, with a short explanation of what each number means.
THE DAILY BRIEF / PRIMARY SOURCES
Read the release.
Find the implication.
The policy and economic releases an investment team follows.
Source dates stay visible. Interpretation stays separate.
POLICY & RATESINFLATIONLABOR & GROWTH
Checking Federal Reserve, BLS, and ECB releases…
Loading observations…
See the numbers & sources
Policy rates are decisions made by central banks. Bond yields are market prices expressed as annual rates. A percentage point is the difference between two percentage rates: 4% to 5% is a rise of 1 percentage point.
How automatic updates work
The panel checks every five minutes while this page is visible and checks again when an old tab is reopened or the connection returns. Providers publish on their own schedules; the server may reuse a response for up to 15 minutes. Each observation keeps its actual date. Saved data is labeled.
Daily market observations are not live prices. Annual economic statistics describe past years. The saved BOJ policy rate and event calendar still require manual verification.
Official releases, not a complete newswire. Checked automatically while this page is visible. Sources publish on their own schedules. Portfolio lenses are fixed research prompts, not AI summaries or investment recommendations.
Where we stand.
Dated observations and explicit evidence gaps.
No crash probability is inferred.
Checking market evidence…
How to interpret these labels
Observed means the stated descriptive condition is met; Developing means partial support. Not confirmed means the available observation does not meet it. Data unavailable means no sufficient current evidence. Criteria are illustrative monitoring rules, not validated trading signals. Saved or older-than-seven-day observations cannot establish current status.
This week’s events
Dates verified against official 2026 calendars on September 14, 2026. Passed events are not assumed to have produced a rate change. Beyond the verified schedule, consult the source calendar.
The possible domino effect
Policy surprise
An unexpected policy path can reprice financing and valuations.
Monitor: Compare the actual announcement with pre-decision expectations.
Could interrupt: An anticipated decision or reassuring guidance.
Funding / currency pressure
A stronger yen can worsen unhedged yen-funded positions.
Monitor: USD/JPY, relative yields, and financing conditions.
Could interrupt: Hedging or an offsetting US policy surprise.
Leveraged losses
Leverage may amplify losses and margin demands.
Monitor: Reliable positioning and margin data, not price correlation alone.
Could interrupt: Low leverage, adequate collateral, or manageable exposure.
Position reductions
Forced sales can transmit stress across assets.
Monitor: Documented liquidation, fund flows, and impaired liquidity.
Could interrupt: Orderly exits and willing buyers.
Broader selling
Selling may spread and persist across markets.
Monitor: Breadth, credit spreads, volatility, and subsequent sessions.
Could interrupt: Resilient earnings, liquidity, and stabilizing prices.
Conditional transmission, not an inevitable sequence. Simultaneous US and Japanese hikes do not necessarily strengthen the yen or cause an equity crash.
MACRO OBSERVATORY / JAPAN AND THE UNITED STATESOPEN RESEARCH THESIS
Yen appreciation.
Global market implications.
Could Japan’s rate reset amplify a US equity selloff?
Follow the mechanism. Test the conditions.
THE QUESTION I’M EXPLORING
If the yen rises rapidly as Japanese funding conditions tighten, leveraged investors may need to reduce overseas risk. My focus is whether that pressure reaches US equities, then persists long enough to affect credit and housing.
CRASH-RISK SCENARIO · NOT A CRASH FORECASTDirection matters. This thesis concerns a rising yen. USD/JPY falls when the yen strengthens. A “yen crash” means the opposite currency move.
Yen value in USDSPY priceREBASED TO 100
Loading market observations…
Data & interpretation
Yen strength = first USD/JPY close ÷ current USD/JPY close × 100. SPY = current close ÷ first close × 100. Dates are matched without filling gaps. FX and US equity daily closes occur at different times; this comparison does not establish causality or a tradeable lead. SPY excludes distributions.
| Date | USD/JPY | Yen index | SPY index |
|---|
THE POSSIBLE TRANSMISSION
- 01
Funding reprices
Japanese rates or policy expectations change.
- 02
Yen strengthens
Foreign assets buy fewer yen when converted back.
- 03
Leverage unwinds
Losses and margin demands may force position cuts.
- 04
Risk assets sell
Liquidity pressure can amplify equity losses.
Conditional links, not an inevitable sequence. Hedging, positioning, policy responses, and market liquidity change the outcome.
THREE PATHS / CHALLENGE THE THESIS
WHAT IF?
Illustrative scenarioStocks move. The yen moves too.
If you buy US stocks with yen, both moves affect what your investment is worth in yen.
SAME DATES FOR BOTH MARKETS
to
Finding shared trading dates…
What you’re testing
Move either slider. The result on the right changes with your assumptions.
Positive means a stronger yen. Negative means a weaker yen.
Positive means stocks rose. Negative means stocks fell.
How to read this comparison
“Observed” uses matched daily USD/JPY and SPY prices for the selected period. The other handle is your hypothetical assumption. Daily FX and stock closes occur at different times, so the comparison does not establish cause and effect.
The combined result is (1 + US stock return) ÷ (1 + yen appreciation) − 1. The ¥100 examples show that arithmetic in simple terms. They are not actual investment balances or measured carry-trade losses. Financing, leverage, dividends, hedging, taxes, and forced selling are excluded.
A mechanism with precedent.
BIS researchers found that leveraged unwinds amplified the initial reaction to weak US macroeconomic news in August 2024. Markets subsequently stabilized. The episode supports the transmission mechanism, while also showing why volatility need not become a lasting crash.
Read BIS Bulletin 90A slower, separate channel.
My housing extension remains a hypothesis. An equity selloff alone does not establish a housing crash. I would look for sustained deterioration in employment, credit availability, mortgage affordability, and local inventory before connecting the two.
Help challenge the thesisResearch framing reviewed September 9, 2026. Price observations are rechecked automatically while this section is visible; source dates remain visible. Personal research, not an employer or institution’s view.
My research and decisions.
Two ways to examine my approach.
When yen strength becomes a portfolio risk.
A focused examination of funding pressure, leveraged unwinds, and US equities. The central question: what evidence distinguishes a temporary shock from persistent stress?
Decisions under uncertainty Three choices built into this research
No automatic crash signal.
Yen appreciation alone does not establish forced selling. The thesis remains conditional on funding pressure, positioning, and broader market stress.
Read the counterargumentChoose on training data.
The strategy demonstration selects among three moving-average pairs using training Sharpe. Inspecting the holdout and changing the design requires a new independent test.
Inspect the selection processMake costs visible.
Entry and exit costs change results. Use the cost control to examine sensitivity before interpreting a return advantage as evidence of a useful strategy.
Stress the assumptionsPILLARS OF INVESTING
A personal introduction. Explore a pillar, or continue to my work below.
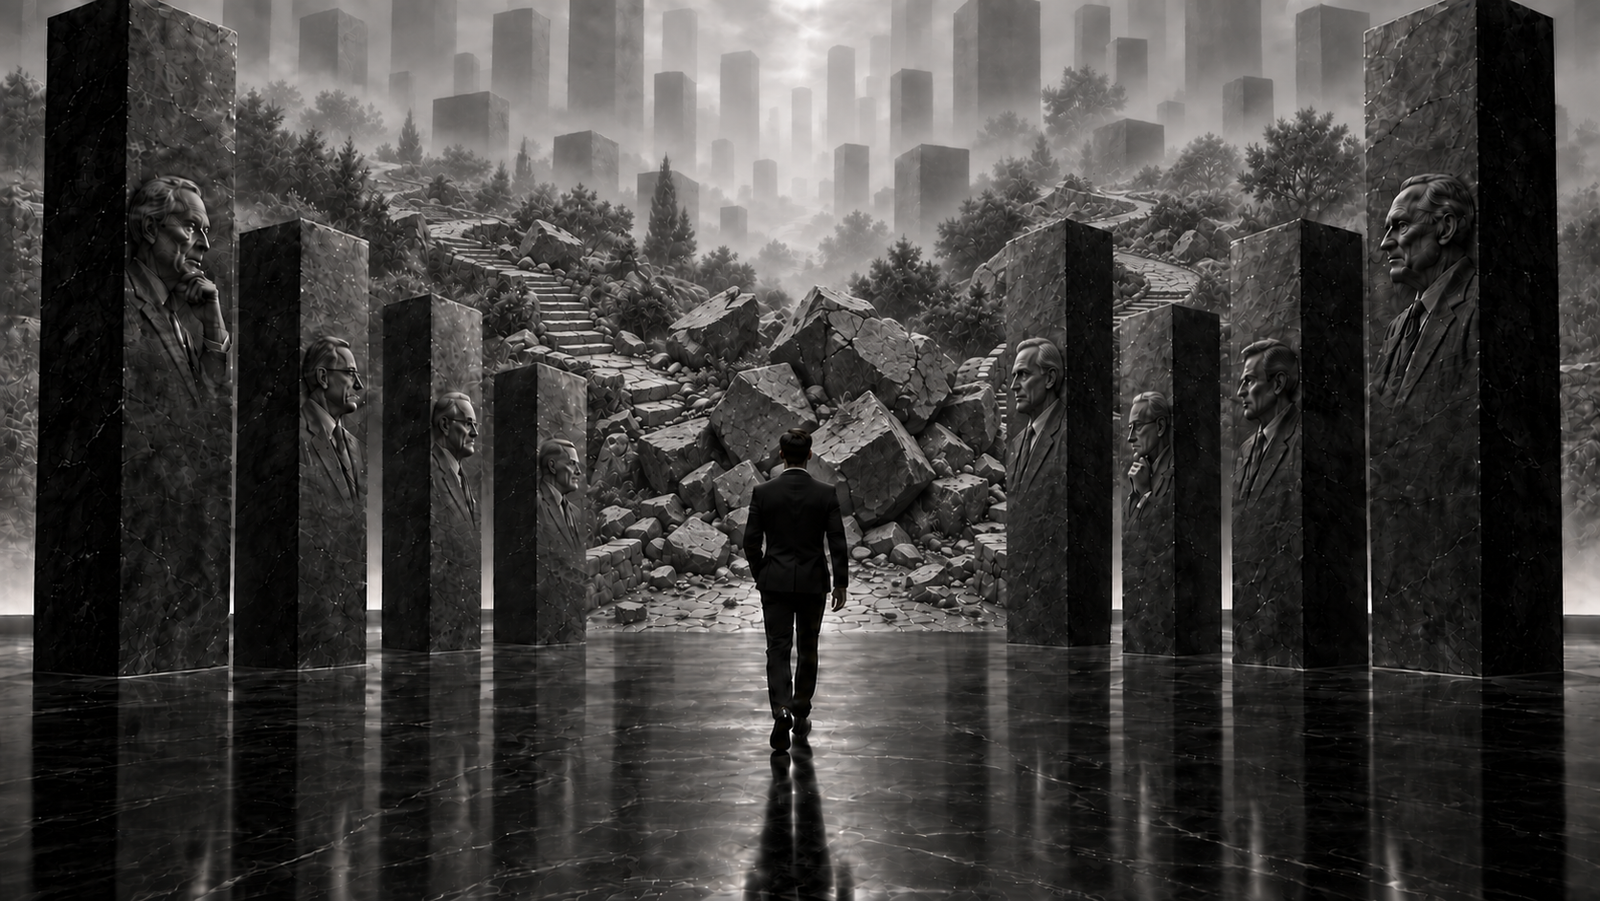
A difficult journey.
Built one step at a time.
The stone road is uneven, and the way ahead is not always clear. I learn from those who came before me, take responsibility for each decision, and keep working toward a path of my own.
PHAT NGO
TECHNOLOGY CONSULTING · FINANCE · DATA
THE VOICEPATIENCE & COMPOUNDING
Warren Buffett
“Our favorite holding period is forever.”Source & context
WHAT I TAKE WITH MEDRAFT
THE PROFESSIONAL PROFILETECHNOLOGY EXPERIENCE. INVESTMENT FOCUS.
Technology experience.
Investment focus.
A background in enterprise systems and data.
A developing focus on investment research and portfolio analytics.
Ernst & Young
Senior Technology Consultant
September 2021 onward
Georgia Tech
M.S. Analytics
Expected May 2027
Python · SQL · R
Data analysis, research workflows,
modeling, and decision support
What I bring to an investment team
Experience organizing complex data, communicating analytical findings, and building repeatable processes. My personal and academic research extends those skills into systematic trading, portfolio construction, and financial text analysis.
01 Translate ambiguous questions into analytical work.
02 Make inputs, assumptions, and limitations visible.
03 Communicate the decision, not just the model.
From enterprise systems to investment work
Data quality
Enterprise reporting experience translates into checking inputs, reconciling discrepancies, and documenting data lineage.
Implementation discipline
Testing and repeatable processes provide a foundation for validating research workflows and identifying operational failures.
Communication
Explaining technical findings to stakeholders supports clear research memos, explicit assumptions, and actionable questions.
Research principles and personal notes
RESEARCH DISCIPLINEPROPOSED PRINCIPLES
A clear process.
An open mind.
The questions behind a defensible decision.
Draft principles for my developing investment approach.
Understand the downside.
Start with what can go wrong, how the risk is measured, and what would invalidate the thesis.
Separate signal from story.
Distinguish a compelling explanation from evidence that survives alternative assumptions and independent evaluation.
Revise with the evidence.
Record the original reasoning, identify what changed, and update the view without rewriting the past.
QUESTIONEVIDENCERISKREVIEW
THE DECISION NOTEBOOKILLUSTRATIVE ENTRIES
Show the reasoning.
Leave a record.
A framework for reviewing decisions.
These examples demonstrate the format, not past trades.
01 / MODEL VALIDATIONDoes the result survive a change in assumptions?
- Initial question
- Is a strategy's apparent edge sensitive to costs, execution assumptions, or the chosen period?
- Evidence to collect
- Results from held-out periods, a record of parameter choices, and sensitivity to more conservative costs.
- What would change the view
- Performance that disappears under reasonable assumptions or relies on a small number of unusual observations.
- Decision status
- No conclusion until the evidence is available.
02 / RESEARCH INTEGRITYDoes the information exist when the decision is made?
- Initial question
- Could a text-based signal rely on revised data or information published after the intended decision time?
- Evidence to collect
- Publication timestamps, dataset versions, feature availability, and the sequence of training and evaluation.
- What would change the view
- A signal that weakens when the historical information set is reconstructed correctly.
- Decision status
- Resolve timing and provenance before interpreting a result.
01 / THE REFLECTIONSREAD. QUESTION. MAKE IT YOUR OWN.
The voices stay.
The thinking is mine.
The source, the context, and a personal reading.
The principles I learn from as I build my own path.
Read the source
pn.
My interpretation
DRAFTIN PRACTICE
Draft reflections for Phat to personalize.
Quotations are attributed and linked to their sources. Interpretations are editorial drafts, not statements by the quoted investors.
I'm a technology consultant with a growing body of work in financial markets and applied analytics.
My interests connect systematic trading, portfolio construction, and AI-assisted research. The question behind that work is simple: how can better evidence lead to better decisions?
EXPERIENCE2021 to present
Ernst & Young
Senior Technology Consultant
EDUCATION
Georgia Institute of Technology
M.S. Analytics · Expected May 2027
FOUNDATION
My full technology & AI profile Georgia State University
B.B.A. Computer Information Systems · 2021
INVESTMENT TEAMS / RECRUITERS / COLLABORATORS
Email PhatLet’s talk.
I’m interested in investment research, portfolio analytics, and investment technology opportunities.
The pillars and journey are a conceptual illustration. Its figures are symbolic; quotations come from the linked publications.
Explore a collaboration
THE COUNCIL / AN OPEN INVITATIONRESEARCH / COLLABORATION / SHARED CREDIT
09Buy a seat.
Buy a seat.
Or build a table.
An invitation to collaborate.
A seat offers access to the conversation. Building a table means creating something worth gathering around. I’m interested in people who bring a thoughtful question, a different perspective, and the willingness to do the work together.
Take a seat.
Challenge a thesis. Walk through a model. Share a paper that changes the conversation. Useful disagreement is welcome.
Start a conversationBuild a table.
Turn a question into a research note, a reproducible experiment, or a useful tool. Agree on the scope, document the assumptions, and share credit for the result.
Shape a collaborationWHERE WOULD YOU CONTRIBUTE?
01 Evidence before conviction.
02 Honest disagreement.
03 Credit where it belongs.